

Expense IQ Money Manager
Handy Apps
- 3.2
- 2.81K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
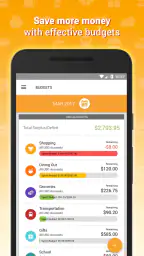
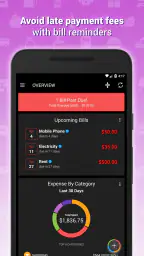
Expense IQ Money Manager Pros and Cons
Pros
- Clear expense categories make spending easy to organize.
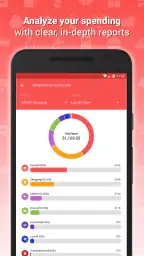
- Useful charts help identify spending patterns quickly.
- Supports recurring transactions for regular bills and income.
- Budget alerts can help prevent overspending.
- Data backup options make it easier to preserve financial records.
Cons
- Some advanced features may require a paid upgrade.
- The interface can feel dated compared with newer finance apps.
- Manual transaction entry may become tedious for frequent purchases.
- Sync options may not be as seamless as bank-linked alternatives.
- Limited sharing features make joint household budgeting less convenient.
 Analysis by All-app
I started using Expense IQ Money Manager because I wanted a clearer picture of everyday spending without turning household budgeting into a full-time project. It is a finance app from Handy Apps, built around recording expenses, planning budgets, and remembering bills. That combination sounds simple, but it becomes useful when several small purchases are spread across a household and nobody has a reliable view of where the money is going.
My experience was mixed in a good way: the app can be practical and approachable, especially if you are willing to enter transactions consistently, but it is not a magic connection between every account and every person in a home. Its strongest role is as a shared reference point for money decisions, not as a replacement for a bank app or a complete family-management system.
Using Expense IQ in a real household
A realistic example is a couple managing groceries, transport, subscriptions, school-related spending, and occasional cash purchases. One person may pay for most things with a card while the other uses cash or a different account. Without a common record, each person remembers only part of the month. Expense IQ gives you a place to record those transactions and compare them with the budget you intended to follow.
I found the app most helpful when I treated it as a daily habit rather than something to open only after money had disappeared. Entering a purchase soon after making it keeps the information useful. Waiting several days makes small cash expenses harder to remember, and a budget can look healthier than reality simply because some transactions have not been added yet.
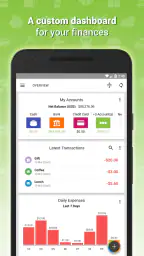
The everyday benefit is not just seeing a total. It is noticing patterns early enough to act. If food spending is rising faster than expected, the household can adjust before the next major bill. If several annual or irregular payments are approaching, the bills reminder can keep them from being forgotten. That kind of awareness is more valuable than a decorative chart that nobody checks.
For a shared device, I would establish a simple routine. The person who makes a purchase records it, while the other person reviews the current picture at an agreed time. This avoids the common problem where one household member assumes the other is tracking everything. The app can support coordination, but the coordination still depends on an agreement between the people using it.
What the setup is really good at
The first useful decision is how detailed to make your categories. I would not create a separate category for every shop. A structure such as groceries, eating out, transport, household costs, personal spending, and recurring bills is easier to maintain. Too much detail creates friction, and friction is dangerous in a budgeting app because users eventually stop recording purchases.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
At the same time, broad categories can hide the reason a budget is failing. I would separate groceries from takeaway meals, for example, because they require different decisions. I would also keep personal spending distinct from shared household spending when two adults need clear boundaries. That distinction makes a monthly conversation less personal: the discussion can focus on the category rather than on who spent the money.
Expense IQ is free to install, which makes it easy to try without committing money at the beginning. The app also includes in-app purchases ranging from a few dollars to well over a hundred dollars per item. I would check the purchase screen carefully before paying, particularly if the app is being used on a device that several people can access. The free starting point is convenient, but the presence of optional purchases means the household should agree on who is allowed to approve them.
The app is rated for Everyone, which suits a general household device from an age-label perspective. That label should not be confused with financial independence or permission to view private spending. A teenager may be able to operate the interface, but that does not mean they should see every household transaction. The sensitive issue is not whether the app is easy to open; it is whether the people sharing the device have agreed on what can be viewed and changed.
Boundaries matter more than the number of features
Before putting shared financial information into any app, I would decide whether the device itself is appropriate. A family tablet left in a common room is not the same as a personal phone. If one person records rent, debt payments, or private purchases, casual access can become uncomfortable even when everyone is acting in good faith.
I would also decide who is responsible for corrections. Duplicate entries, forgotten cash payments, and transfers between accounts can distort a budget quickly. If everybody edits everything, fixing one mistake may create another. A better household rule is to let one person maintain the main record while the other reports missing expenses and checks the totals. This is a workflow choice rather than a feature claim, but it makes the app much more dependable.
Another useful boundary is separating tracking from authorization. Expense IQ can help you document a purchase, but I would not treat it as proof that a purchase was approved. A recorded transaction tells you what someone entered; it does not establish who agreed to the spending. For shared money, that distinction prevents arguments when a category is exceeded.
I would keep official bank statements and receipts for anything important. The app is a planning and tracking tool, so it works best alongside the financial records you already rely on. If the numbers in the app and the bank do not match, the bank record should be the starting point for investigation. This matters especially when several people enter transactions at different times.
Coordinating without turning budgeting into surveillance
The healthiest use I found is collaborative rather than supervisory. Instead of checking every purchase to judge another person, use the app to answer practical questions: How much remains for groceries? Which bill is due next? Did we include the irregular expense we discussed? That approach keeps the focus on shared planning.
For couples, I would review the budget once a week and make a short list of changes. The review should include pending bills, recent cash spending, and categories that are approaching their limits. A short, regular check is easier to sustain than a long monthly audit. It also gives both people a chance to correct a forgotten item before the information becomes too old.
For a household with older children, I would use the app selectively. It may be useful to let a child record their own allowance-related spending or learn how categories work, while keeping adult accounts and private purchases outside the shared view. The app can become a teaching aid, but the lesson should be about planning and trade-offs, not about giving a child unrestricted access to family finances.
One non-obvious advantage of this approach is that a budget can become a conversation starter before a problem becomes urgent. A rising category does not automatically mean someone behaved irresponsibly. It may reveal a change in commuting, food prices, medical needs, or a temporary household project. Looking at the trend together encourages explanation rather than blame.
There is also a trade-off. Shared data is only as accurate as the least consistent participant. If one person records every coffee and another records only large payments, the resulting comparison is misleading. I would rather have a simple system that everyone follows than a sophisticated one that only one person maintains.
Age, trust, and the limits of shared access
The Everyone content rating makes the app broadly suitable from a store-classification standpoint, but money management still requires adult judgment. Younger users may understand categories and totals without understanding the consequences of exposing account details or changing a budget. I would demonstrate the process and define exactly what the child may enter before allowing independent use.
I would also avoid using a shared device as a substitute for separate personal boundaries. If two adults have different incomes, obligations, or private spending, one combined view may not be comfortable. In that situation, a jointly maintained household budget can cover shared costs while each person keeps personal tracking elsewhere. Expense IQ is more useful when the level of visibility matches the relationship and the purpose.
Trust is especially important because a financial record can look authoritative even when it contains manual errors. I would teach every user to check the date, amount, category, and account before saving an entry. A small mistake repeated over several weeks can produce a false sense of control. The app helps organize information; it cannot independently verify that every entry is correct.
For older adults or anyone less comfortable with finance apps, the interface may still require patience. I would start with only the essential categories and one bill reminder, then add complexity after the routine feels natural. A household should not make one person responsible for correcting everybody else's entries without giving them enough time and confidence to do it.
How it compares with the usual alternatives
Compared with a paper notebook, Expense IQ is better for looking back at categories and keeping reminders in one place. Paper can be wonderfully private and flexible, but it does not make reviewing a month as convenient. The app is the stronger choice when several types of spending need to be organized repeatedly.
Compared with a spreadsheet, it is more approachable for someone who does not want to design formulas, tabs, and summaries. A spreadsheet gives an experienced user greater control over custom calculations and shared editing rules, though. If your household needs detailed forecasting, complex split payments, or a carefully designed audit trail, a spreadsheet may be the better tool.
Compared with a bank's own app, Expense IQ has a different purpose. A bank app is the authoritative place to inspect actual account activity, while this app is better suited to planning categories, recording cash, and thinking about upcoming bills. I would not replace the bank app with it. I would use both, with the bank confirming reality and Expense IQ helping shape decisions.
Compared with newer budgeting services that focus on automatic account connections or collaborative dashboards, Expense IQ feels more dependent on user discipline. That can be a weakness if you want everything imported automatically. It can also be a strength if you prefer deciding how expenses are categorized instead of accepting whatever an automatic system guesses. Manual entry takes effort, but it gives you a clearer understanding of your own spending.
Performance, compatibility, and long-term practicality
The current version is 2.3.2, and the listed minimum operating system is Android 4.4. That broad compatibility is useful for an older household phone or tablet that cannot run many recent apps. It also means the app may appeal to people who want to give an older device a practical purpose rather than replacing it immediately.
Still, compatibility alone should not decide whether a shared device is suitable. An older device may be slower, have a worn battery, or be left unlocked more often. I would consider the physical security of the device and the privacy of the room where it is stored. A finance app on an old tablet can be convenient, but convenience should not override sensible access boundaries.
The app has passed one million installs, with an average rating of 3.2 from around twenty-three thousand ratings and roughly two thousand eight hundred written reviews. Those figures suggest a sizable user base but also a divided experience. I would not choose it solely because many people have installed it. The important question is whether your household is comfortable with the manual tracking style and the way you want to coordinate spending.
Because it is a free finance app with optional purchases, I would begin with a small trial: enter one week of household expenses, add the bills that matter most, and compare the result with the bank statement. That test reveals more than a quick glance at the feature list. If nobody keeps the entries current during the trial, paying for extras will not solve the underlying problem.
Who should use it, and who should choose something else
I would recommend Expense IQ to a person who wants one place for expense tracking, budget planning, and bill reminders, especially when some spending happens in cash or outside a single bank account. It is a sensible fit for a couple that can agree on categories and for a small household that wants a shared overview without building a spreadsheet.
I would be more cautious for a family that needs strict account separation, automatic synchronization across several users, or formal approval controls. The app may still help with a shared household budget, but it should not be presented as a complete system for managing every person's access to money. In that situation, a bank tool, spreadsheet, or service designed around multiple accounts may be a better foundation.
I would also skip it if you know you dislike manual entry. No budget app can compensate for missing transactions, and this one is most valuable when the record is kept current. Someone who wants a nearly automatic experience may become frustrated and conclude that the budget is inaccurate, when the real issue is the amount of upkeep required.
My household verdict
After looking at it as both a personal tracker and a shared household tool, I see Expense IQ as a practical organizer rather than a complete financial command center. Its useful combination of spending records, budgets, and bill reminders can bring order to ordinary money decisions, particularly when a household agrees on who records transactions and who reviews them.
My main advice is to set boundaries before entering private information, keep categories simple, and compare the app with official account records regularly. Use it to coordinate goals, not to monitor people. If everyone follows the same recording routine, it can make a shared budget feel manageable. If nobody agrees on responsibility or privacy, the app will only make the confusion more visible.
Handy Apps has made a free finance app that is approachable enough for everyday use and compatible with older Android devices. The optional purchases deserve attention, and the modest average rating shows that it will not suit everyone. For me, the deciding factor is the household workflow: Expense IQ works best when it supports a clear agreement between people, rather than trying to replace one.
That makes it worth trying for a household that wants a straightforward manual system and is prepared to maintain it. I would recommend a short, honest trial before relying on it for important planning. If the entries stay current and the shared boundaries feel comfortable, it can become a useful part of the monthly routine. If automatic importing, strict privacy separation, or advanced collaboration is essential, I would choose a different finance solution instead.
Frequently Asked Questions
What is Expense IQ Money Manager, and what can I use it for?
Expense IQ Money Manager is a personal finance app designed to help you organize income, expenses, bills, budgets, savings goals, and account balances in one place. After reviewing its main tools, I found it particularly useful for users who want a clearer picture of daily spending. You can categorize transactions, monitor financial habits, and review reports instead of relying on notes or spreadsheets.
Does Expense IQ Money Manager support multiple accounts and currencies?
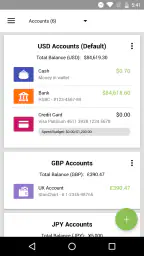
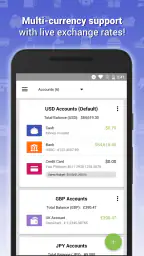
Yes, the app is designed to manage more than one financial account, such as cash, bank accounts, credit cards, and savings. This makes it easier to track money across different places without mixing everything together. Currency support and exchange-related options may depend on the app version and device settings, so users who regularly handle international finances should confirm the currently available currency features before downloading.
Can I create budgets, track bills, and receive reminders?
Expense IQ Money Manager includes tools for planning spending and keeping up with recurring financial obligations. You can set budgets for categories, record regular bills, and use reminders to reduce the risk of forgetting payment dates. In my experience, these features are most helpful when transactions and due dates are entered consistently. The app works best as an active planning tool rather than a passive record of expenses.
Is my financial information safe when using Expense IQ Money Manager?
Because the app can contain sensitive information about spending, accounts, and personal finances, privacy should be considered before use. Expense IQ may offer security features such as an app lock or passcode protection, depending on the platform and version. However, users should review the current privacy policy, permissions, backup options, and synchronization settings, and avoid entering unnecessary banking credentials or highly confidential information.
Is Expense IQ Money Manager free, and are there any limitations?
Expense IQ Money Manager may be available as a free download, but some advanced functions can depend on the edition, platform, or optional premium features. Restrictions may involve reports, synchronization, backups, customization, or other convenience tools. Before installing, check the current store listing for pricing, subscriptions, advertisements, and in-app purchases. This is especially important if you need full access to every budgeting and account-management feature.


